Micron Technology (NASDAQ: MU) saw its share price surge by almost 5 % in early trading on Monday, later easing to a gain of roughly 1.8 % by 10:10 a.m. Eastern time. The rally followed a note from Stifel analyst Brian Chin, who reiterated his buy recommendation and maintained a $1,500 price target for the memory‑chip maker.
Analyst outlook ahead of earnings
Chin’s endorsement comes with less than a week remaining before Micron reports its fourth‑quarter results on September 30. In his commentary, the analyst referenced the broader Wall Street consensus, which projects a 350 % increase in Micron’s revenue to about $51 billion and a tenfold rise in earnings to $31.35 per share. While Chin does not dispute those forward‑looking figures, he cautions investors to anticipate a “more measured rate‑of‑upside than in recent quarters.” In practice, that means the company may still post earnings beats, but the magnitude of those beats could be smaller than the outsized surprises seen in prior periods.
One factor tempering expectations is Micron’s growing reliance on supply agreements that lock in pricing. Such contracts provide a larger, more predictable revenue base, reducing the likelihood of dramatic upside surprises even as the overall top‑line remains sizable.
AI demand and memory‑upcycle dynamics
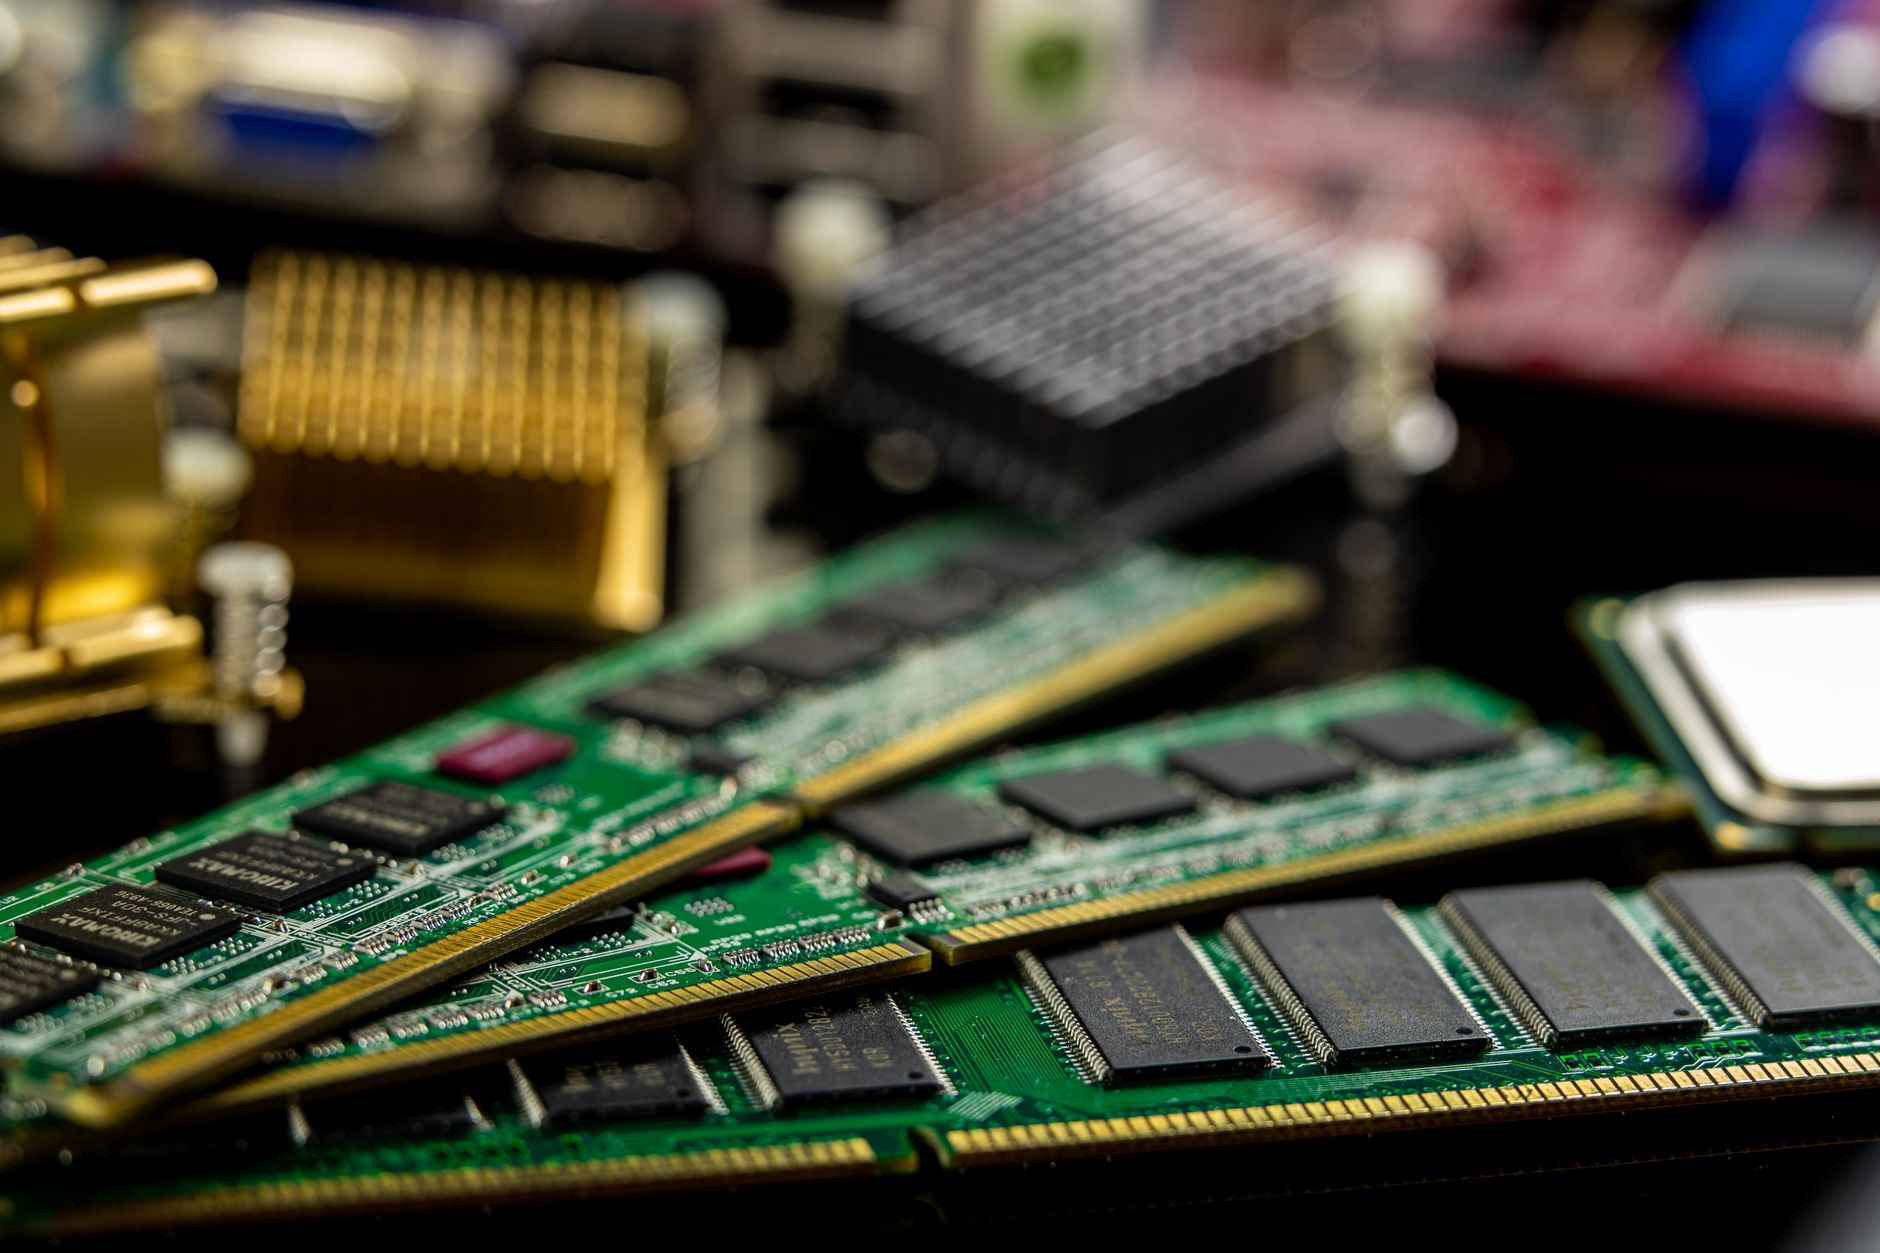
Despite the tempered earnings outlook, Chin highlighted that the AI revolution continues to drive demand for high‑performance memory. He described the durability of the current memory up‑cycle as “under‑appreciated,” noting that both DRAM and high‑bandwidth memory (HBM) markets remain undersupplied. In Chin’s view, it is reasonable to expect 15 % to 20 % annual growth in chip volume through 2027, accompanied by rising profit margins.
These dynamics, combined with the stock’s valuation—trading at less than 23 times earnings—support Chin’s continued bullish stance. He argues that, given expectations of triple‑digit earnings growth over the next five years, Micron remains an attractive buy at current levels.
Contrasting viewpoints and broader market context
Not all market commentators share the same enthusiasm. The Motley Fool Stock Advisor’s analyst team recently released a list of ten stocks it believes offer the best upside potential, and Micron did not make the cut. The publication cited historical examples, such as Netflix and Nvidia, to illustrate the potential magnitude of returns from its selected picks, but Micron was absent from that particular shortlist.
Investors weighing a position in Micron must therefore balance the firm’s strong AI‑driven demand outlook and predictable revenue streams against the more modest earnings upside anticipated by Stifel and the omission from other prominent buy‑list recommendations.
As the company approaches its Q4 earnings release, market participants will likely focus on whether the firm can deliver growth in line with the optimistic revenue forecasts while navigating the more measured earnings expectations set by analysts like Brian Chin. The stock’s near‑term price action—spiking early in the session before settling—reflects a market that is digesting both the positive analyst endorsement and the nuanced guidance on future performance.

Norman Pearlstine is the Executive Editor and Co-Founder at News Raise. With over two decades of experience across financial journalism, corporate governance, and market analysis, Norman leads the editorial direction and ensures strict adherence to journalistic accuracy and ethics.